What Is Inheritance Tax? Singapore’s History and the Latest Debate
Imagine saving for your first condo while another buyer can fund the downpayment with rental income from properties their parents left them. Same viewing, very different starting points.
That’s the concern behind the latest Parliament discussion about property wealth and inheritance. And yes, Monopoly came up.
Singapore currently has no estate duty for deaths on or after 15 February 2008. The latest speeches haven’t changed that, but they’ve reopened a question worth asking: how much of a property head start should pass from one generation to the next? IRAS explains the current position.
What MPs actually proposed
During the Finance (Income Taxes) Bill debate on 6 October 2026, MP Elysa Chen called for the Government to study a progressive holding tax on multiple investment residential properties. She described a property market where newcomers face a Monopoly game already tilted against them. CNA’s account of her speech sets out that proposal.
MP Shawn Loh separately suggested an inheritance tax for high-value properties as a way to reduce wealth inequality. His speech summary makes that distinction clear.
These are different taxes. A holding tax applies while you own the properties; an inheritance tax applies when wealth passes on after death.
Jeffrey Siow said these issues were outside the scope of the bill and invited MPs to raise parliamentary questions at a later sitting, according to Mothership’s coverage. This was a policy discussion, not a new inheritance-tax announcement.
What is inheritance tax?
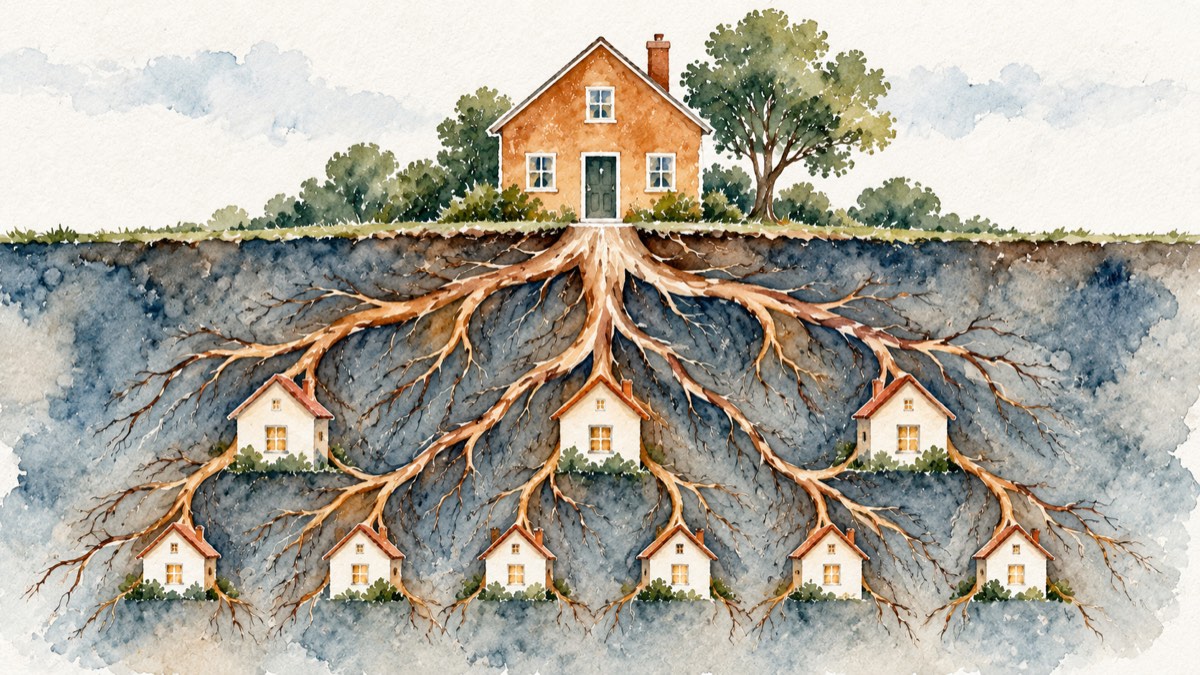
Broadly, it’s a tax on wealth passed on when someone dies. That wealth can include homes, cash, investments and business interests.
There are 2 main ways to do it:
- Estate tax: assess the deceased person’s estate as a whole, before distribution to beneficiaries.
- Inheritance tax: assess what each beneficiary receives, potentially with different exemptions or rates.
The OECD distinguishes the taxes this way. Singapore’s old version was called estate duty.
For a simple illustration, imagine someone leaves $6 million equally to 3 children. An estate-based system starts with the $6 million estate; a recipient-based system starts with each child’s $2 million inheritance, then applies its rules.
That’s an illustration, not a proposed Singapore threshold. There’s no new rate or exemption to calculate from these speeches.
Why tax something parents leave their children?
The main argument is fairness between generations. Someone inheriting several properties gets an advantage that someone relying entirely on salary may struggle to catch up with, even if both work equally hard.
Supporters argue that taxing large transfers can raise public revenue and reduce the concentration of wealth within families. The OECD’s research finds that a well-designed inheritance tax can help improve equality of opportunity, particularly when it targets large transfers.
The objection is equally easy to understand: “I worked, saved and paid taxes. Why tax my family again?”
Parents want to provide for their children; society also has an interest in giving children without wealthy parents a fair chance.
The difficult part is deciding where ordinary family support ends and a large inherited fortune begins. In Singapore, the price of a single home makes that question especially sensitive.
Singapore had estate duty long before 2008
This isn’t a new idea imported from an overseas headline. Singapore’s Estate Duty Act traces back to an ordinance that took effect on 1 July 1929, during British rule.
By the final years before abolition, the main exemptions were $9 million for residential properties and $600,000 for other assets. Those were separate categories, not a blanket $9.6 million allowance that could be used however you liked. MOF explained those exemptions in 2005.
After applicable exemptions and deductions, the rates were:
| Taxable estate value | Historical rate |
|---|---|
| First $12 million | 5% |
| Amount above $12 million | 10% |
These are the old rates, for deaths from 28 February 1996 to before 15 February 2008. IRAS retains the historical calculation rules.
So the old system didn’t simply take a percentage of every family’s home. Its exemptions mattered a lot.
Why did Singapore abolish it?
In the 2008 Budget speech, paragraphs 4.71–4.78, then Finance Minister Tharman Shanmugaratnam laid out the trade-offs.
The much lower exemption for non-residential assets disproportionately affected middle- and upper-middle-income estates compared with wealthier ones. Raising it would have made an already narrow tax base even smaller.
There was also an economic argument: removing estate duty could encourage wealth to be invested and built up in Singapore, including assets brought here from abroad. The Government judged abolition to be in Singapore’s wider interest.
But it retained property tax as a way to tax wealth, highlighting that property tax was harder to avoid through tax planning.
We shouldn’t assume that reviving an old tax would automatically produce a fairer result. We need to ask who would actually pay it.
Does the Monopoly argument hold up?
I think it captures the problem of unequal starting positions quite well. Inheriting a rental portfolio changes your options in a way that getting a pay rise doesn’t.
But Monopoly is a board game. Real housing markets also have tenants, mortgages, new construction and public housing.
An investor-owned home that’s rented out still houses someone. It may reduce the homes available for owner-occupiers to buy, but it isn’t automatically a home sitting empty.
And the policies address different problems. If the concern is owning a large portfolio today, a recurring holding tax targets that directly; if the concern is wealth passing down through generations, inheritance taxation targets that transfer.
Neither guarantees cheaper homes. The effect would depend on which properties are affected, how owners respond, rental demand and housing supply.
I’d be wary of any argument that jumps straight from “tax landlords more” to “young couples can afford homes”. There’s quite a bit missing in between.
What would a sensible new tax need?
I’m open to a tax on very large inheritances. But I’d want answers to these questions before supporting a particular scheme:
- Who is it meant to reach? Inheriting one shared family home is different from receiving a substantial investment portfolio. The threshold should reflect that.
- How would families pay? A valuable house doesn’t come with cash in the letterbox. Payment deferrals or instalments deserve consideration where an immediate bill could force a sale.
- Would gifts and trusts create easy escape routes? A tax that can be sidestepped by transferring assets earlier may miss the very people it targets. The OECD identifies lifetime gifts and reliefs as important tax-design issues.
- Why tax property alone? If equally valuable cash or investment portfolios receive different treatment, that needs a convincing reason.
- What happens alongside existing taxes? Any proposal should be assessed together with property tax, stamp duties and tax on rental income.
These are questions for a possible design, not features the Government has announced.
Also, any threshold needs periodic review. A policy aimed at exceptional wealth shouldn’t quietly expand to more ordinary estates just because asset prices rise.
What property investors should know now
There’s no new inheritance-tax bill to budget for from this discussion. But having no estate duty doesn’t mean inherited property has no tax consequences.
IRAS says ABSD isn’t payable when the inheritance follows a will, intestacy law or Muslim inheritance law. However, an inherited Singapore residential property, including a partial share, can count towards your property ownership when you make a subsequent purchase.
That can change the ABSD position on your next home. Inheriting a property and buying another one afterwards are separate events.
Income generated by an estate after death can also remain taxable. IRAS distinguishes that income tax from the abolished estate duty.
Policy position checked on 7 October 2026. This is a general explainer, not advice on a particular estate or transaction; check the applicable rules before acting.
My view: the case for taxing very large inherited fortunes deserves a serious hearing. So does the case for protecting a family’s home and savings from a badly designed tax.
I own a property website, so obviously I’m interested in property doing well. I’d also like the next generation to have a chance to buy one.